The global fashion landscape is undergoing a profound structural realignment, driven by regulatory scrutiny, shifting consumer demographics, volatile financial markets, and systemic economic models that continue to favor overproduction. From the turbulent public market debut of ultra-fast-fashion giant Shein in Hong Kong to the quiet dismantling of size-inclusive ranges amid the rise of GLP-1 weight-loss therapeutics, the industry is grappling with fundamental questions regarding its economic viability, ethical responsibilities, and ecological future. Furthermore, investigations into charity clothing exports and the shifting financial burdens of decarbonisation highlight an entrenched supply chain dynamic where systemic reform remains secondary to corporate profit margins.
Fast-Fashion Market Debuts and Investor Skepticism: The Shein Case Study
The recent entry of Shein onto the Hong Kong stock exchange marked a turbulent milestone for the ultra-fast-fashion titan, as its shares plummeted by as much as 10% within the initial minutes of trading. This sharp downward correction compressed the company’s overall market valuation, signaling mounting investor caution regarding the long-term viability and regulatory exposure of hyper-accelerated retail models.
This Hong Kong flotation represents the culmination of a protracted, globally contested strategy by Shein to secure a public listing. Previous attempts to float on major Western financial hubs—most notably the New York Stock Exchange and the London Stock Exchange—were effectively stonewalled by intense regulatory friction, bipartisan political pushback, and sustained advocacy campaigns from labor rights organizations. Regulators and lawmakers in the United States and Europe repeatedly raised alarms over Shein’s opaque supply chain architecture, its utilization of complex trade loopholes like the de minimis exemption, and persistent allegations concerning labor exploitation and forced-labor risks within its manufacturing networks.
Financial analysts note that the tepid Hong Kong debut reflects a broader institutional wariness. As global scrutiny intensifies around environmental, social, and governance (ESG) metrics, companies reliant on single-use, high-volume apparel models face escalating compliance costs and reputational risks. The drop in share value underscores a growing disconnect between private-equity valuation expectations and public market willingness to absorb the existential risks tied to unsustainable manufacturing practices.
The Economics of Circularity: Why Sustainable Brands Struggle to Survive
While fast-fashion giants navigate public market skepticism, independent sustainable brands face an entirely different—yet equally perilous—survival crisis. The recent bankruptcy of pioneering circular denim brand MUD Jeans has reignited critical discussions within the industry regarding the structural economic disadvantages faced by enterprises attempting to build regenerative business models.
Industry analysts emphasize that the contemporary fashion economy is fundamentally engineered to reward linear production: the more units a brand manufactures and sells, the lower its relative per-unit costs and the higher its profit margins. Conversely, sustainable brands that invest in circular design, durable raw materials, ethical labor practices, and end-of-life garment take-back schemes must shoulder the heavy financial burdens of product longevity and waste management.
Shayeza Walid, writing in the Business of Fashion, highlighted the fatal flaw in current market frameworks: asking individual, values-driven businesses to independently build and sustain a circular fashion ecosystem is mathematically unsustainable. When the prevailing macroeconomic incentives continuously reward volume-driven overproduction, sustainable pioneers are left exposed to inflationary pressures, high capital costs, and a lack of institutional financial backing. Market experts argue that without systemic regulatory interventions—such as extended producer responsibility (EPR) laws that penalize virgin resource extraction and subsidize recycling infrastructure—the economic pendulum will continue to swing heavily in favor of linear fast fashion.
The Contradictions of Corporate Decarbonisation: Shifting Costs to the Supply Chain
As global brands face mounting pressure from governments and consumers to achieve net-zero carbon emissions, a disturbing trend has emerged regarding how these environmental targets are financed. According to recent tracking data from the Business and Human Rights Resource Centre, major international fashion brands are increasingly shifting the capital expenditure and operational costs of decarbonisation onto their upstream suppliers.
Decarbonising the fashion supply chain—transitioning factories to renewable energy, upgrading machinery to improve energy efficiency, and implementing water-saving technologies—requires significant upfront capital investment. However, rather than absorbing these transition costs or providing long-term financial partnerships to their manufacturing partners in the Global South, dominant brands are maintaining strict pricing pressures and short-term purchasing practices.
Labor leaders and human rights advocates have raised urgent concerns that this dynamic creates a false dichotomy between green transitions and worker welfare. Factories forced to absorb the multi-million-dollar costs of green compliance without corresponding increases in purchase order prices frequently resort to margin-squeezing. Consequently, the financial squeeze often trickles down directly to the factory floor, resulting in suppressed wages, forced overtime, and precarious working conditions. Observers stress that genuine sustainability cannot be achieved through greenwashing exercises that externalize financial burdens onto vulnerable manufacturing workforces.
The GLP-1 Era and the Corporate Retreat from Size Inclusivity
In consumer markets, a quiet yet significant rollback is underway regarding body positivity and size inclusivity. Over the past year, major fashion retailers across the United States and Europe have quietly scaled back or entirely eliminated extended-size collections (XXL and above), leaving millions of consumers scrambling to find garments that properly fit their bodies.
This sudden contraction in size ranges coincides with the widespread adoption of GLP-1 receptor agonist weight-loss therapeutics, such as Ozempic and Wegovy. Fearing a permanent demographic shift in consumer body sizes, risk-averse retail executives have panicked, reducing inventory allocations for plus-size apparel under the guise of shifting demand curves.
However, consumer advocacy groups and retail industry analysts argue that this corporate narrative is fundamentally misleading. Comprehensive market research indicates that demand for inclusive sizing remains robust, and the sudden scarcity of larger garments is a manufactured supply-side shortage rather than a reflection of consumer needs. As traditional retailers abandon plus-size shoppers, consumers are increasingly turning to peer-to-peer secondhand marketplaces and niche independent labels to source well-fitting clothing. Sociologists and fashion historians note that this regression highlights the industry’s historical reluctance to view diverse human bodies as a permanent, foundational market segment rather than a temporary trend.
Uncovering the Global Charity Clothing Export Machine
Beyond the retail floor, investigative journalism continues to expose the deeply opaque pathways of post-consumer textile waste. A landmark investigation published in The Telegraph by journalist Tansy Hoskins revealed the hidden economic structures governing the export of unsellable clothing donated to Western charity shops.
While charitable organizations rely heavily on the unpaid labor of local volunteers to keep charity shops operational and generate revenue for social causes, the surplus clothing that cannot be sold locally enters a multi-million-dollar international export pipeline. Hoskins’ investigation traced the complex corporate webs behind these textile export businesses, uncovering unexpected beneficiaries at the top of the financial hierarchy—including high-net-worth nobility such as the Crown Prince of Liechtenstein.
The findings illuminate the neo-colonial reality of global textile waste management, where millions of tons of discarded garments from the Global North are shipped to countries in the Global South, frequently overwhelming local textile economies and contributing to environmental degradation. The investigation serves as a stark reminder of the hidden human and ecological costs subsidized by well-meaning consumers who donate garments under the assumption that they are exclusively serving local philanthropic purposes.
Innovation Amid Crisis: Case Studies in Alternative Materials
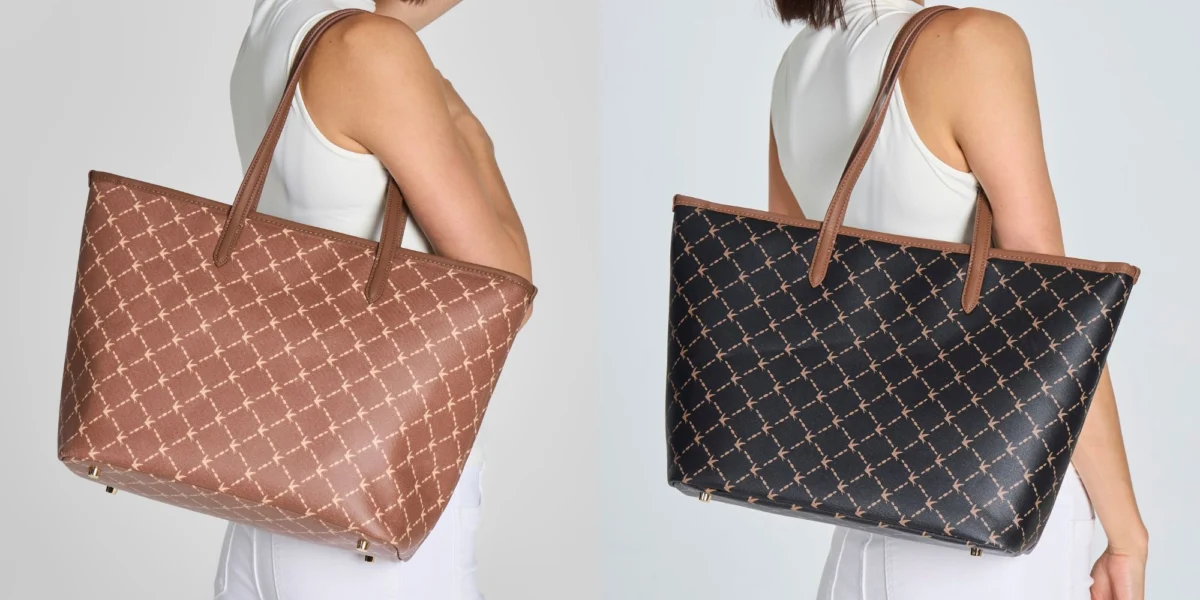
Despite the overwhelming systemic challenges facing the industry, individual purpose-driven brands continue to push the boundaries of material innovation and ethical accountability. A notable development in the sustainable accessories sector involves the brand Svala, which recently introduced a new vegan tote bag named the Vita.
Following the sudden supply chain unavailability of several next-generation plant-based materials—such as MIRUM and Piñatex—Svala was forced to re-engineer its material sourcing pipeline. The brand partnered with a specialist coated-canvas manufacturer in China to develop an alternative material: a printed coated canvas crafted from Global Organic Textile Standard (GOTS) certified organic cotton, finished with a durable, PVC-free TPU coating.
Crucially, Svala’s manufacturing partner is actively working toward achieving formal B Corporation certification by 2027, reflecting an industry-wide recognition that material innovation must be matched by rigorous, verified operational transparency. While such initiatives demonstrate the agility of independent sustainable labels, industry experts maintain that technological and material substitutions must be accompanied by sweeping macro-level regulatory reforms if the global fashion sector is to achieve authentic, long-term ecological balance.