The contemporary fashion landscape is undergoing a profound structural reckoning, characterized by turbulent public market debuts, shifting consumer demographics, systemic economic roadblocks for ethical labels, and deeply entrenched supply chain controversies. As the industry grapples with the dual pressures of environmental accountability and shifting cultural norms, recent developments highlight an uncomfortable truth: the global fashion system continues to reward high-volume, resource-intensive business models while penalizing those attempting genuine reform. From the rocky stock market arrival of ultra-fast-fashion giant Shein to the quiet disappearance of plus-size collections in the wake of new weight-loss drugs, the sector is experiencing unprecedented friction between profit-driven motives and ethical imperatives.
Shein’s Rocky Market Debut and the Obstacles of Going Public
The challenges facing the upper echelons of fast fashion were thrown into sharp relief when Shein officially launched its long-anticipated stock market debut on the Hong Kong exchange. In the immediate minutes following its market launch, Shein shares tumbled by as much as 10%, sharply depressing the company’s overall valuation and signaling investor unease.
This dramatic dip is merely the latest chapter in a protracted, hurdle-laden effort by the ultra-fast-fashion titan to transition into a publicly traded entity. Previously, Shein’s attempts to float on prominent Western financial hubs, including the New York Stock Exchange and the London Stock Exchange, were systematically stalled or blocked. Regulators, institutional investors, and advocacy groups repeatedly raised severe concerns regarding the company’s opaque supply chain practices, allegations of labor exploitation, environmental degradation, and the heavy reliance on hyper-accelerated micro-trends.
The Hong Kong debut was viewed by market analysts as a strategic pivot to bypass Western regulatory scrutiny. However, the immediate sell-off demonstrates that public markets are increasingly sensitive to the reputational and regulatory risks associated with the ultra-fast-fashion business model. Financial experts note that as global scrutiny over forced labor, carbon footprints, and customs loopholes intensifies, companies built on extreme disposability may find public capitalization increasingly difficult to sustain.
The Billionaire Prince and the Dark Side of Charity Clothing Exports
While fast-fashion giants face headwinds on trading floors, the back-end realities of global clothing disposal continue to generate controversy and unexpected profit streams. A comprehensive investigative report by journalist Tansy Hoskins, published in The Telegraph, has uncovered a startling paradox at the heart of the secondhand economy: the vast mountains of unsellable clothing donated by well-meaning citizens to charity shops are frequently bundled, exported to the Global South, and monetized by unexpected beneficiaries.
According to Hoskins’ long-read investigation, a significant portion of the profits derived from exporting low-grade, discarded charity textiles ultimately makes its way to the Crown Prince of Liechtenstein. This revelation exposes the complex, highly financialized corporate structures underpinning international textile recycling and export businesses. While local volunteers keep neighborhood charity shops afloat through unpaid labor and community dedication, the surplus inventory that cannot be absorbed locally feeds a multi-million-dollar export pipeline. This system frequently overwhelms destination markets in developing nations, creating localized ecological crises while channeling wealth upward to European aristocracy, far removed from the grassroots origins of the donated garments.
Economic Barriers and the Collapse of Sustainable Pioneers
Compounding these supply chain inequities is the structural hostility of mainstream fashion economics toward genuinely sustainable brands. The fragility of the ethical fashion sector was recently underscored by the high-profile bankruptcy of MUD Jeans, a pioneer in circular denim production.
Analyzing the fallout of such collapses, industry commentators highlight that the fundamental economics of the fashion industry actively work against sustainable enterprises. Brands committed to circularity—such as taking responsibility for end-of-life care, garment recycling, repair services, and utilizing certified organic or regenerative materials—must shoulder immense financial burdens that traditional fast-fashion competitors entirely bypass.
The core issue lies in an economic model that continually rewards volume and speed. By externalizing the true environmental and social costs of production, conventional brands maintain artificially low price points, capturing the lion’s share of consumer spending. Sustainable brands, by contrast, must price their goods to reflect ethical labor and closed-loop manufacturing, pricing themselves out of mainstream affordability. As industry analysts observe, asking individual, purpose-driven businesses to independently construct a sustainable fashion ecosystem is fundamentally insufficient. Without sweeping macroeconomic reform—such as extended producer responsibility (EPR) legislation and penalties for virgin material extraction—the existing economic architecture will continue to penalize sustainability while subsidizing excess.
The Shrinking Size Spectrum: Plus-Size Closures in the GLP-1 Era
Beyond production and retail economics, the industry is also witnessing a disturbing regression in physical inclusivity. In the United States and other major consumer markets, the rapid mainstream adoption of GLP-1 receptor agonist weight-loss medications (such as Ozempic and Wegovy) has triggered an unexpected corporate reaction: fashion brands are quietly downsizing their size ranges and scaling back on plus-size inventories.
An in-depth investigation by The Guardian revealed that numerous apparel retailers have begun phasing out XXL and extended-size clothing lines, forcing consumers who require larger sizes to scour secondhand marketplaces or specialty stores in search of wearable options. While corporate boardrooms frequently attempt to justify these reductions by citing shifting sales metrics or a localized decline in demand, independent industry experts strongly dispute this narrative.
Data indicates that the demand for diverse, inclusive sizing remains robust, driven by a population that has long fought for representation in retail spaces. Activists and consumer advocates argue that the sudden contraction of plus-size offerings reflects lingering fatphobia and corporate risk aversion rather than true market obsolescence. By retreating to narrower sizing matrices, brands are alienating millions of consumers and reversing hard-won progress toward body inclusivity under the guise of shifting medical and cultural trends.
Decarbonization Pressures Shifted Downward to Vulnerable Suppliers
As global regulatory bodies push for climate action, major fashion brands are increasingly setting ambitious decarbonization targets. However, research from the Business and Human Rights Resource Centre indicates that these corporate sustainability pledges are frequently built on the backs of vulnerable manufacturing partners.
The Centre’s ongoing tracking of global brand purchasing practices reveals a troubling trend: rather than absorbing the capital expenditure required to transition facilities to renewable energy or low-impact manufacturing, major brands are shifting the financial burden of decarbonization directly onto their suppliers. Factories in the Global South—already operating on razor-thin profit margins dictated by relentless competitive bidding—are told to green their operations without receiving corresponding financial support or long-term purchasing commitments from the multinational brands they serve.
Labor leaders have expressed deep alarm over this dynamic. They point out that while corporate sustainability reports highlight soaring percentages of "green" supply chains, this transition does not automatically translate to improved working conditions, higher wages, or safer environments for garment workers. Instead, cash-strapped suppliers may cut corners elsewhere—such as wages or safety compliance—to finance the costly technological upgrades demanded by Western brands.
Innovation Amid Crisis: Svala’s Material Evolution
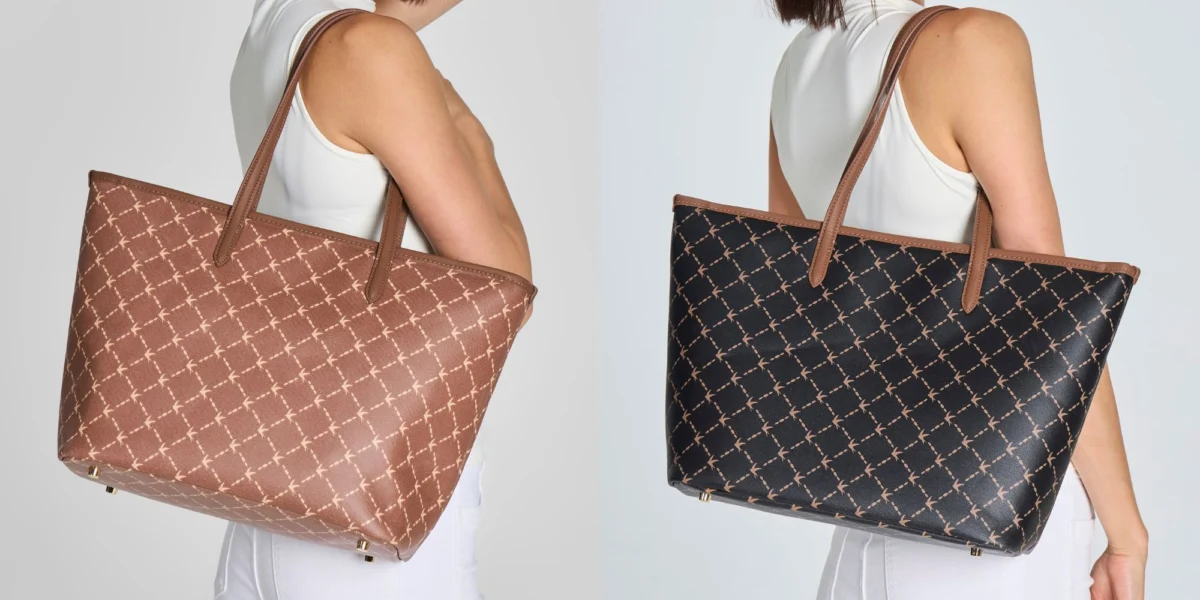
Despite the systemic headwinds facing the broader industry, certain independent, highly rated brands continue to pioneer lower-impact material alternatives. A notable example is the sustainable accessories brand Svala, which recently navigated supply chain disruptions by engineering a novel textile solution.
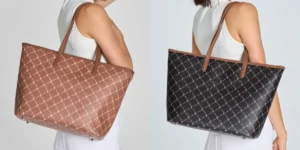
Following the commercial unavailability of several next-generation biomaterials—such as MIRUM and Piñatex—Svala partnered with specialized manufacturing experts to develop the "Vita" tote bag. The product utilizes a printed coated canvas crafted from GOTS-certified organic cotton, finished with a durable, PVC-free TPU coating. The manufacturing partner, based in China, is actively progressing toward official B Corporation certification by 2027, demonstrating that ethical supply chain development remains an ongoing, iterative process.
Implications for the Future of Global Apparel
The convergence of these events paints a complex and sobering picture of the global fashion economy. The struggles of ultra-fast-fashion on public exchanges, coupled with the systemic exploitation exposed in charity export networks and supplier decarbonization shifts, illustrate an industry at war with its own externalities. Simultaneously, the retreat from size inclusivity and the financial collapse of circular pioneers like MUD Jeans underscore that the market currently offers little insulation for companies trying to do the right thing.
For consumers, policymakers, and industry watchdogs, the path forward requires moving beyond superficial corporate pledges. True reform will demand binding international regulations that hold major brands financially accountable for their entire supply chains, protect garment workers from bearing the costs of environmental transitions, and enforce equitable sizing and manufacturing standards across the board. Until structural economics are redesigned to penalize overproduction and reward true circularity, the fashion industry will continue to cycle through crises of its own making.