The global luxury watch market is currently undergoing a structural transformation characterized by a pivot toward high-frequency product launches, digital-first marketing strategies, and a distancing from traditional consumer-engagement models. Data from the Federation of the Swiss Watch Industry (FH) indicates that the sector exported approximately 14.6 million timepieces in recent reporting periods. While these figures suggest high volume, industry analysts note that the vast majority of these sales are driven by a broad consumer base rather than the dedicated enthusiast segment. This shift has prompted a critical examination of how heritage brands and conglomerates manage their public image, media relations, and the retail experience in a post-pandemic economic landscape.
The Evolution of the Industry Landscape
For decades, the luxury watch industry relied on a predictable, centralized calendar. Events such as Baselworld and the Salon International de la Haute Horlogerie (SIHH) served as the annual anchors for the market. During this era, brands synchronized their research and development cycles with these exhibitions, presenting major novelties within a concentrated window. This provided the media and the public with a focused narrative, allowing for a structured period of education and absorption regarding new horological advancements.
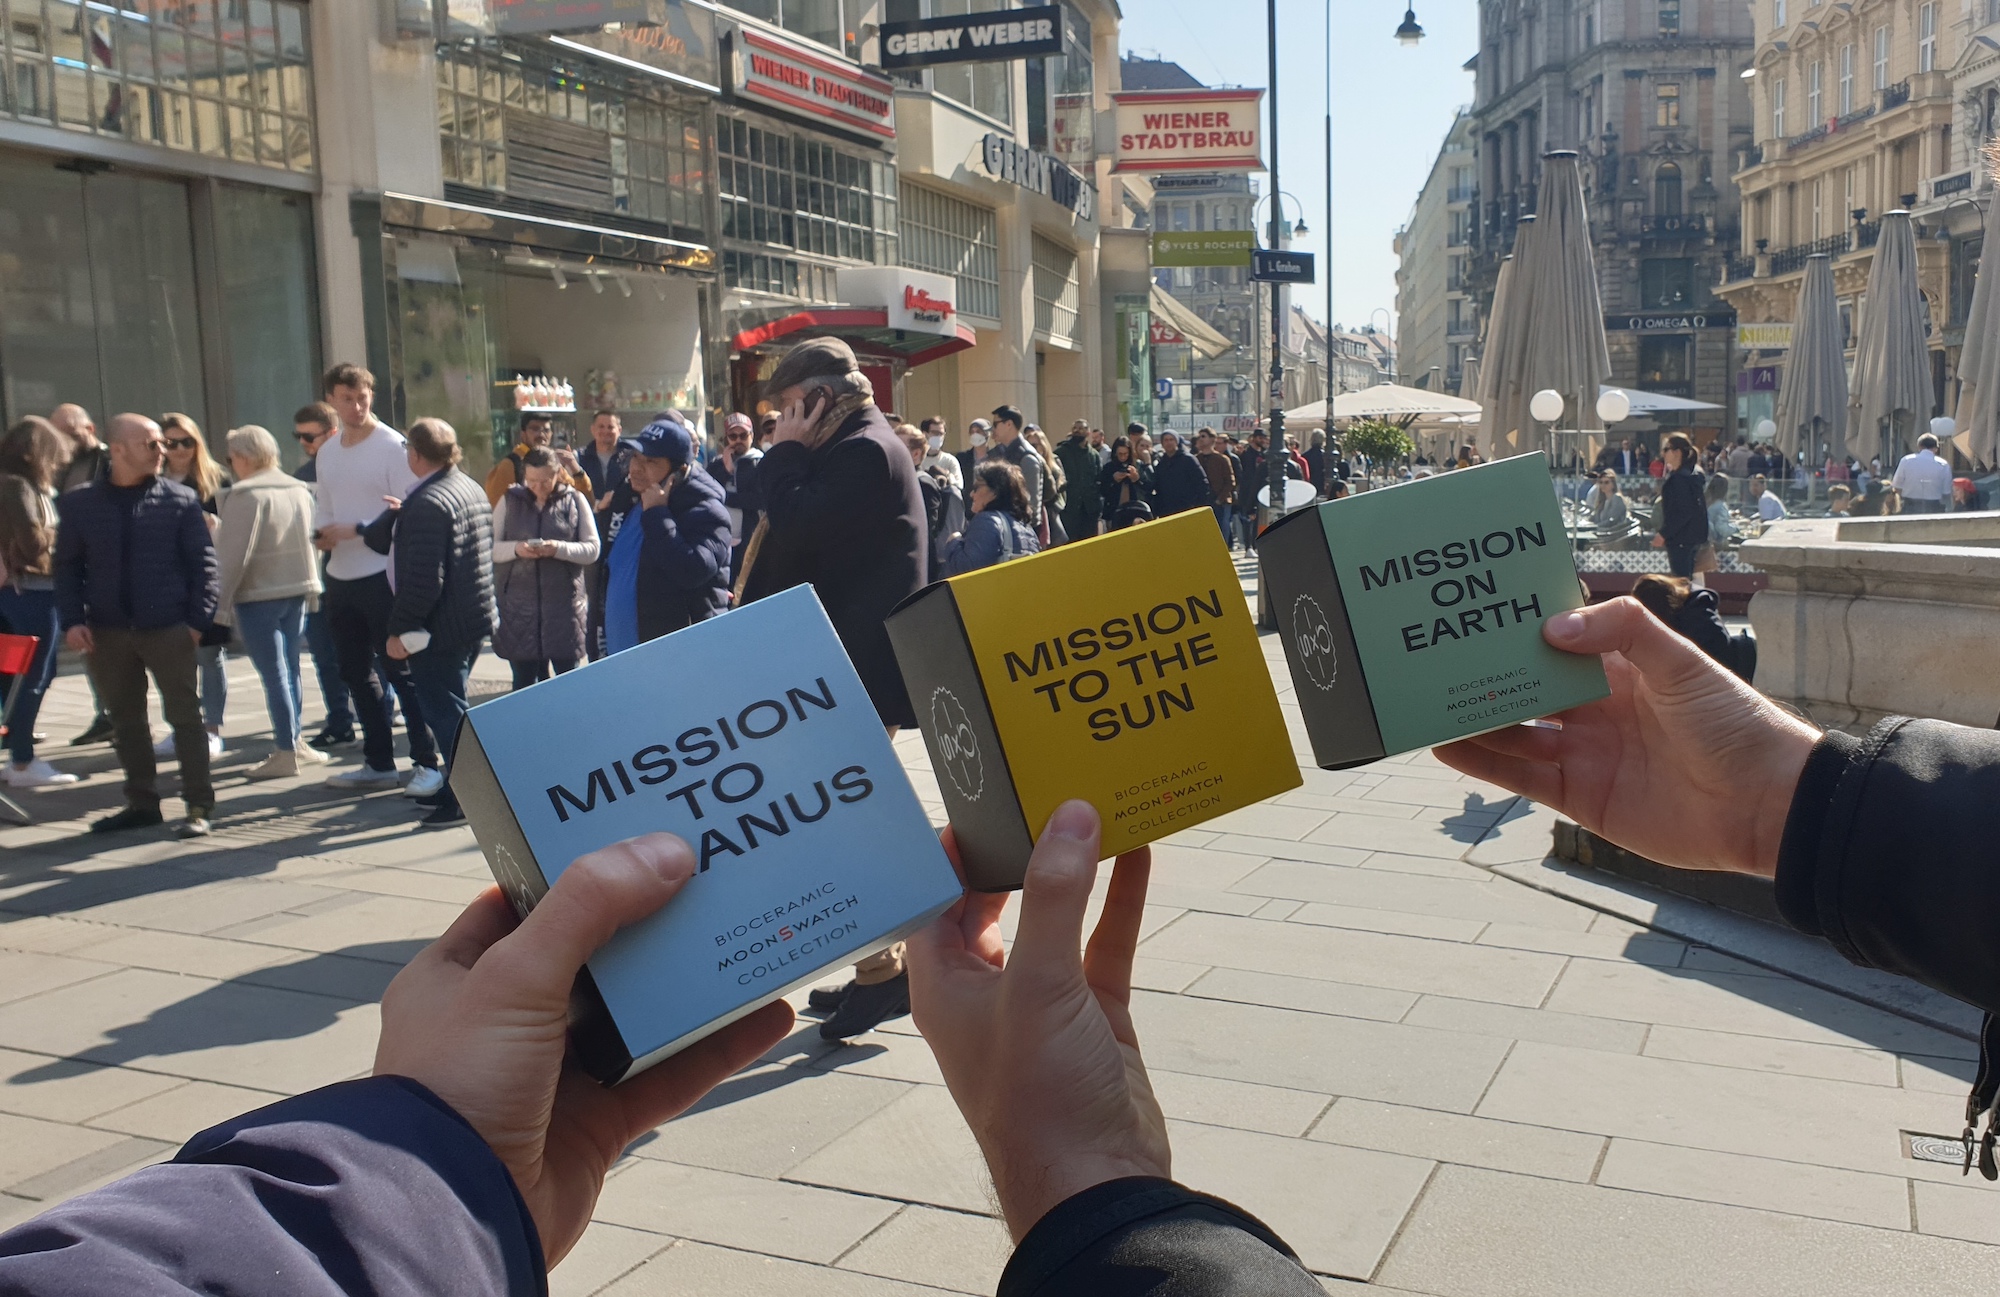
In recent years, this stability has eroded. The dissolution of Baselworld and the rise of Watches & Wonders Geneva (WWG) as the dominant industry fair signaled a move toward a more fragmented release schedule. Major houses, including those under the umbrellas of Rolex, LVMH, and Richemont, have increasingly adopted mid-year, off-cycle, and rolling release strategies. While this approach attempts to maintain a constant stream of news flow in the digital age, it has simultaneously diluted the impact of individual product launches and created an information-heavy environment that often leaves the average consumer and specialized media struggling to keep pace.
Data and Market Dynamics
The current state of the industry is defined by an influx of inventory and an aggressive pricing strategy. According to secondary market reports and retail data, the surge in product output has outpaced consumer demand in several key segments. The "beige wall" phenomenon—a term used by critics to describe the aesthetic and experiential monotony at major trade fairs—is often cited as a symptom of a broader industry-wide risk aversion.
A brief look at historical marketing efforts highlights this shift. In the late 2000s and early 2010s, brands invested heavily in high-fidelity 3D-animated movement visualizations and deep-dive technical storytelling. This content was designed to bridge the gap between complex mechanical engineering and the consumer’s understanding of value. Today, while production technology has become more accessible and cost-effective, the prevalence of such in-depth, educational content has declined, replaced largely by short-form video content and aesthetic-focused imagery on social media platforms.

Shifts in Retail and Media Relations
The relationship between brands, the media, and the end consumer has undergone a significant recalibration. The traditional boutique experience, once centered on personalized service and the transmission of brand heritage, is now frequently criticized for its lack of accessibility. Retailers often struggle to maintain a balance between the "waitlist" culture—driven by high-demand stainless steel sports models—and the need to cultivate a welcoming environment for new entrants into the luxury market.
Media relations have also been affected by this transition. In the automotive sector, brands frequently invite media to participate in pre-launch technical briefings and experiential events to foster a deeper understanding of the product. By contrast, many watch brands have reduced their engagement with specialized journalism, opting instead for direct-to-consumer digital channels. While this gives brands greater control over their narrative, it limits the independent analysis and historical context that journalists provide, which is essential for building long-term consumer trust.
Implications for the Future of Horology
The long-term implications of these shifts are twofold. First, there is the risk of alienating the enthusiast base, which has historically acted as the primary brand ambassador for luxury timepieces. Without the "story" behind the product, a watch becomes merely a luxury accessory, susceptible to the same trend-based volatility as fast fashion. Second, the reliance on hype-driven releases—such as limited editions and collaborative projects—can create a bubble that does not reflect the underlying health of the brand’s core portfolio.

Market observers suggest that the current accumulation of unsold inventory in warehouses is a direct result of this disconnect. When the industry prioritizes volume and high-frequency cycles over consumer relationship-building, the resulting friction in the marketplace becomes inevitable.
Industry Responses and Strategic Adjustments
While official commentary from major conglomerates remains focused on long-term sustainability and brand exclusivity, some entities have begun to recognize the need for a more inclusive approach. Organizations such as the Fondation de la Haute Horlogerie (FHH), which manages the Watches & Wonders platform, have implemented broader public access days to foster a more direct connection with the community. Similarly, smaller, independent watchmakers have found success by doubling down on transparency, direct communication, and intimate community events, effectively filling the void left by larger houses.
However, the consensus among industry experts is that a return to a more deliberate and transparent engagement model is required to sustain growth. This includes:

- Restoring the Depth of Narrative: Moving beyond 15-second social media reels to provide substantial, technically accurate information that justifies price points and brand positioning.
- Standardizing the Retail Experience: Ensuring that boutique staff are empowered to educate, rather than merely gatekeep, ensuring that the luxury experience remains inclusive and professional.
- Strategic Synchronization: While the industry will likely never return to the rigid schedules of the 20th century, a more organized release calendar would prevent the current saturation and allow for a more meaningful consumer connection to new products.
Conclusion
The watch industry stands at a crossroads. The transition to a digital-first, high-frequency model has provided short-term benefits in terms of visibility but has simultaneously eroded the pillars of storytelling and consumer trust that have sustained the sector for generations. As inventory levels rise and consumer fatigue becomes a more tangible reality, the industry’s ability to pivot back toward a "customer-first" mentality—one that values the enthusiast and the novice alike—will likely determine its trajectory in the coming decade. Whether the industry chooses to refine its current path or return to its roots of mechanical excellence and open engagement remains the central question for stakeholders across the global watch market.