The global fashion landscape faces a complex confluence of financial restructuring, shifting consumer demographics, and persistent structural challenges, highlighted by SHEIN’s rocky public debut, the retreat of size-inclusive collections amid the rise of GLP-1 weight-loss drugs, and systemic economic hurdles facing eco-friendly brands.
SHEIN’s Rocky Public Debut Marks a New Low for Fast-Fashion Valuation
Ultra-fast-fashion giant SHEIN experienced a tumultuous entry onto the public market this month, with its shares tumbling by as much as 10% within minutes of opening on the Hong Kong stock exchange. The immediate sell-off significantly deflated the company’s valuation, compounding a prolonged and difficult journey toward a public flotation.
Background context reveals that this Hong Kong debut followed multiple failed attempts to list on major Western financial hubs, including the New York Stock Exchange and the London Stock Exchange. Regulators and institutional investors in both regions repeatedly blocked or discouraged SHEIN’s IPO applications, citing mounting scrutiny over its opaque supply chain practices, allegations of labor exploitation, and questions regarding compliance with modern slavery legislation.
Financial analysts note that the weak market reception in Hong Kong signals growing investor wariness surrounding the long-term viability and regulatory exposure of ultra-fast-fashion business models. While the company has attempted to clean up its corporate image by appointing external auditors and pledging sustainability transparency, the immediate valuation drop demonstrates that market skepticism remains deeply entrenched.
The Hidden Supply Chains of Charity Shop Exports
Beyond the high-stakes world of corporate stock listings, investigative reporting continues to expose the less glamorous realities of global textile waste. An in-depth investigation published in The Telegraph by journalist Tansy Hoskins uncovered a surprising financial pipeline connecting local charity shop donations to elite wealth.
The investigation revealed that profits generated from exporting unsellable, surplus clothing donated to high-street charity shops ultimately flow to an unexpected ultimate beneficiary: the Crown Prince of Liechtenstein. The long-read explores the intricate, often opaque corporate structures that govern the international clothing export market, where millions of tons of discarded garments find their way to markets in the Global South.
Industry watchdogs point out that this trade exposes significant loopholes in circular economy frameworks. While charity shops are widely perceived as localized community assets, the backend management of textile surplus often operates as a lucrative global commodity broker, largely hidden from the everyday donors who believe their contributions are exclusively supporting domestic charitable causes.
Economic Realities: Why Sustainable Fashion Brands Struggle to Survive
While fast-fashion giants grapple with public market skepticism, independent eco-friendly brands face an equally daunting existential crisis rooted in macroeconomic design. Following the high-profile bankruptcy of pioneering circular denim brand MUD Jeans, industry analyses have brought the structural flaws of the fashion economy into sharp focus.
Writing for the Business of Fashion, analyst Shayeza Walid detailed the severe financial disadvantages sustainable labels encounter. Unlike traditional linear business models—which profit directly from manufacturing and selling maximum volume—sustainable and circular brands must internalize the costs of end-of-life care, garment recycling, and resource stewardship.
"Asking individual businesses to build a more sustainable fashion system will only get the industry so far if the economics of the existing one continue to reward making and selling more," Walid argued, underscoring the systemic market failure that penalizes companies attempting to operate ethically. Economic experts suggest that without systemic policy interventions, such as extended producer responsibility (EPR) mandates and financial subsidies for circular infrastructure, pioneering eco-friendly labels will continue to struggle against legacy competitors subsidized by high-volume, low-cost production models.
The Shrinking Market for Plus-Size Fashion in the GLP-1 Era
A demographic and cultural shift is simultaneously reshaping the retail floor, as the widespread adoption of GLP-1 receptor agonist weight-loss drugs in Western markets prompts major apparel retailers to quietly scale back their size-inclusive ranges.
Over recent weeks, reports have highlighted a noticeable decline in the availability of XXL and extended-size clothing across prominent high-street and mid-market brands. Consumers seeking inclusive sizing have increasingly reported being forced to turn to secondhand marketplaces to find garments that fit, reversing years of hard-fought progress toward body positivity and size diversity in mainstream fashion.
While several corporate executives have publicly attributed the reduction in extended-size inventory to a drop in consumer demand, independent retail experts strongly dispute this claim. Industry data indicates that demand for inclusive sizing remains robust, but retailers are proactively adjusting inventory allocations in anticipation of demographic shifts tied to pharmaceutical weight-loss trends. Critics argue this reactive downsizing alienates a significant portion of the consumer base, reinforcing historical exclusion under the guise of shifting market trends.
Decarbonization Pressures Shift Financial Burdens Onto Vulnerable Suppliers
Sustainability initiatives within major global fashion brands are also drawing scrutiny for how their costs are distributed throughout the supply chain. According to recent tracking data from the Business and Human Rights Resource Centre, global fashion brands are increasingly shifting the financial burden of decarbonization onto their manufacturing and raw material suppliers.
While brands frequently publish ambitious net-zero targets and carbon-reduction milestones, the operational costs required to upgrade factory infrastructure, transition to renewable energy sources, and implement low-carbon production methods are routinely absorbed by tier-one and tier-two suppliers. These suppliers—often operating on razor-thin margins—are given compliance deadlines without proportional financial backing from the multinational brands they service.
Furthermore, labor rights leaders have raised alarms that corporate decarbonization drives do not inherently correlate with improvements in worker welfare. In many instances, the heavy capital expenditure required for green transitions diverts factory budgets away from fair wage distribution and workplace safety enhancements, exacerbating pre-existing labor vulnerabilities in manufacturing hubs across the Global South.
Industry Innovation: Sustainable Materials and B-Corp Aspirations
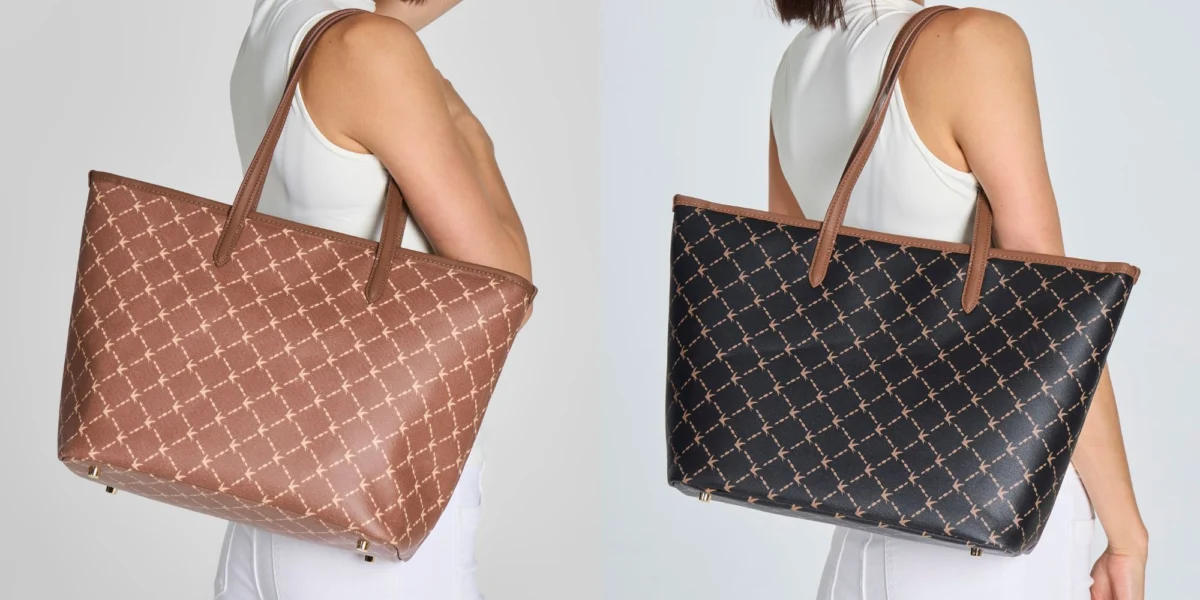
Amid systemic economic and ethical challenges, select independent brands continue to pioneer operational pivots and material innovations. One notable development involves the sustainable accessories brand Svala, which faced supply chain disruptions after several next-generation biomaterials—such as MIRUM and Piñatex—became commercially unavailable.
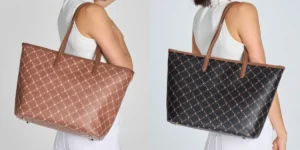
In response, Svala collaborated with material suppliers to engineer a novel vegan alternative: the Vita tote bag. Constructed from a printed coated canvas utilizing GOTS-certified organic cotton combined with a durable, PVC-free thermoplastic polyurethane (TPU) coating, the product represents a shift toward traceable, lower-impact material engineering.
The manufacturing process is executed in partnership with a specialized coated-canvas production facility based in China, which is currently undergoing rigorous auditing to achieve B Corporation certification by 2027. Industry analysts view such adaptive supply chain strategies as a necessary blueprint for independent brands navigating the volatility of next-generation material markets.
Broader Industry Implications and Outlook
The convergence of these developments underscores a critical inflection point for the global fashion industry. The market punishment of SHEIN’s stock debut suggests that investors are growing increasingly sensitive to supply chain opacity and regulatory risk, even as ultra-fast consumption models retain immense market share. Concurrently, the financial collapse of circular pioneers like MUD Jeans and the scaling back of plus-size apparel illustrate that current market economics actively punish inclusivity and sustainability unless supported by systemic regulatory reform.
As global supply chains adapt to decarbonization mandates and shifting consumer demographics driven by pharmaceutical interventions, the onus remains on legislators, corporate leadership, and institutional investors to establish frameworks that reward ethical manufacturing, fair labor practices, and true circularity rather than prioritizing short-term volume extraction.